To live in Bali in 2026 you can choose from four families of health cover, and none of them does everything. France's CFE (Caisse des Français de l'Étranger, the state-backed fund for French nationals abroad) advertises "from" prices of 57 EUR/month under 30 (JeunExpat) and 87 EUR/month over 30 (MondExpat, with no health questionnaire and no age limit), with cover starting immediately if you join before leaving or within 3 months of settling in; but it reimburses on the basis of French statutory rates, far below what Bali's private hospitals charge, which is why it is usually paired with a top-up policy. Private international insurance starts at around 1,020 EUR/year at age 30, 1,500 EUR/year at 45 and 2,000 EUR/year at 60 for entry-level plans (80 to 300 EUR/month for "first-euro" cover depending on the tier): this is the category where medical evacuation is normally written into the contract, an item billed at 20,000 to more than 100,000 USD from Bali. Private Indonesian insurance costs 3 to 8 million IDR a year at age 30, with no evacuation in most policies. BPJS Kesehatan, the public scheme, comes to Rp 35,000 to 150,000 a month (as of 2 August 2026), but it is aimed at foreigners who work in the country for at least 6 months, with no English-language service and no evacuation. The French foreign ministry calls it "imperative" to cover all medical costs and repatriation, and warns that Indonesian hospitals will not treat you without an insurer's guarantee of payment or a credit card number. Two rules follow: sign before you fly, and check the evacuation cover before you look at the price.
Why does the choice come down to evacuation rather than the doctor's visit?
A GP consultation in Bali costs 12 to 50 EUR in a private clinic (12 to 30 EUR according to a French assistance company, 20 to 50 EUR according to a comparison site updated on 14 August 2026); at hospital level, a Bali-based broker records 10 to 30 USD in the public system and 40 to 100 USD in international private hospitals. A specialist: 30 to 100 EUR.
The bill changes scale the moment a night in hospital becomes necessary: 3 to 10 million IDR a night in a private hospital (180 to 600 EUR). A serious emergency with no insurance runs to 20,000 to 50,000 USD and beyond; surgery after a scooter accident is put at 8,000 to 20,000 EUR by the French-speaking expat community. Beyond what the island can treat, "an evacuation to Singapore or France will have to be considered" (France Diplomatie, the French foreign ministry's travel advisory).
| Item | Range recorded in 2026 |
|---|---|
| GP consultation | ≈ 12 to 50 EUR in a private clinic; 40 to 100 USD in an international private hospital |
| Specialist consultation | ≈ 30 to 100 EUR |
| Night in a private hospital | 3 to 10M IDR (≈ 180 to 600 EUR) |
| Surgery after a scooter accident | 8,000 to 20,000 EUR |
| Serious emergency without insurance | 20,000 to 50,000 USD and beyond |
| Evacuation on a commercial flight with medical escort | 20,000 to 40,000 USD |
| Air ambulance to Singapore | 50,000 to 100,000 USD (broker); 25,000 to 80,000 USD (international insurer) |
| Air ambulance from a remote island | 50,000 to 150,000 USD and beyond |
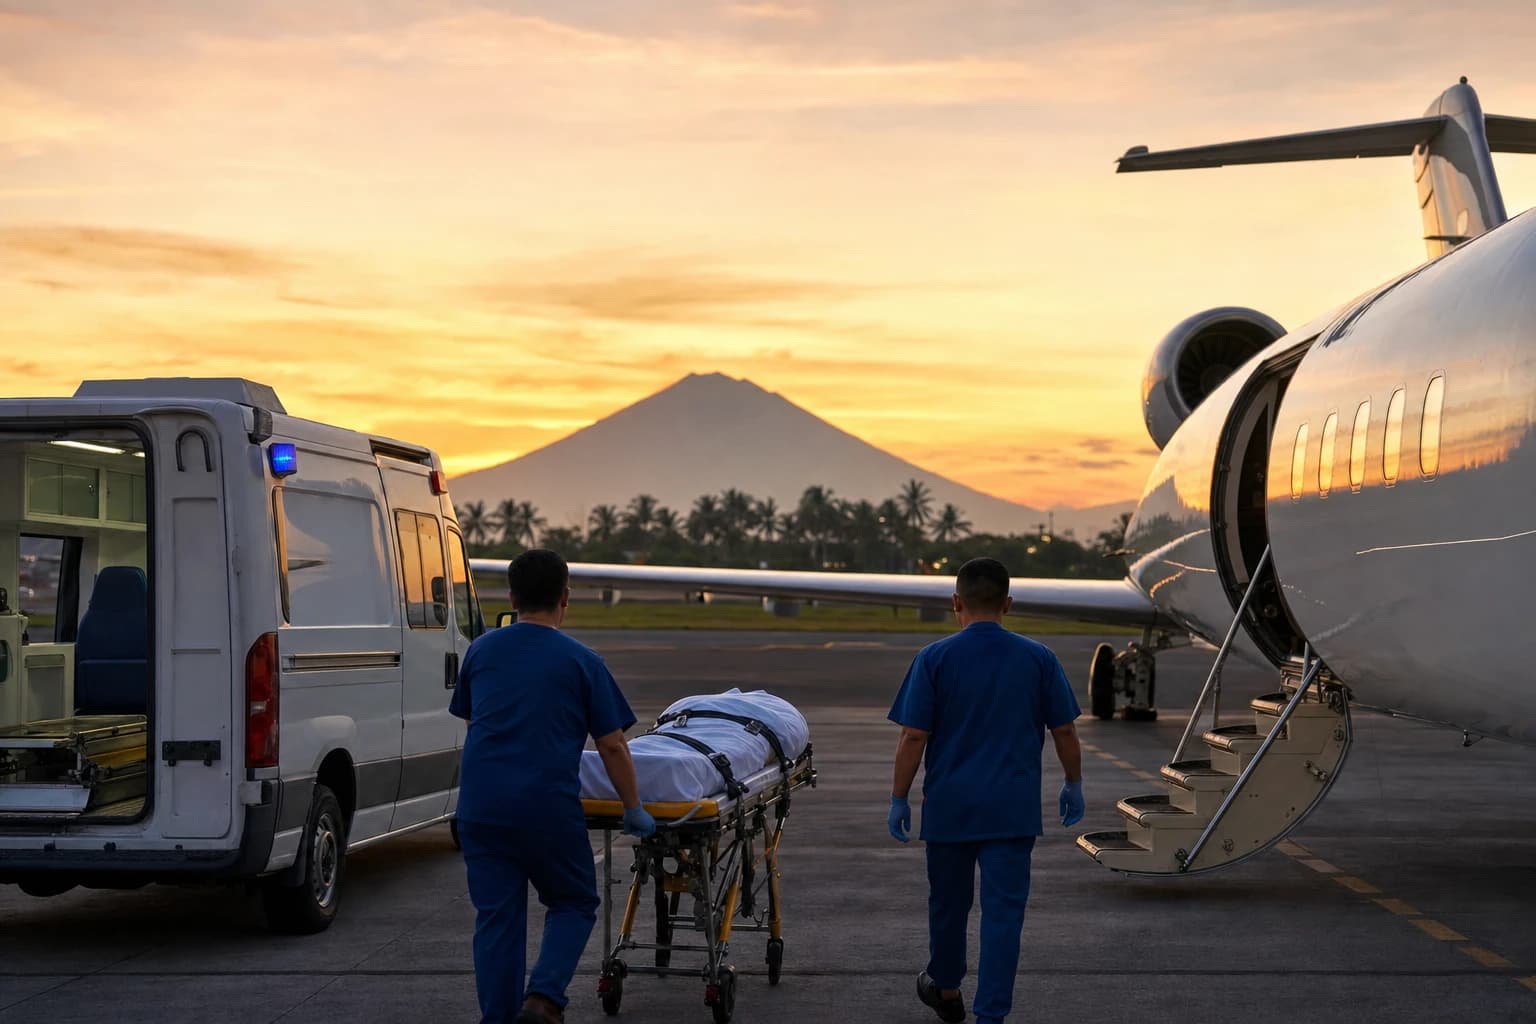
Evacuation figures vary with the mode of transport and the source (20,000 to 45,000 EUR on the French community side). Keep the order of magnitude in mind, 20,000 to more than 100,000 USD, and above all this: neither BPJS nor most Indonesian policies cover this item. The broker quoted recommends a ceiling of at least 100,000 USD.
One last point, and everything else follows from it: "Indonesian hospitals provide no treatment until they have a guarantee of payment from an insurer or, failing that, a credit card number" (France Diplomatie, which also recommends private hospitals over public ones). The deposit demanded by Bali's private hospitals: 500 to 5,000 USD according to the same broker. It is the same logic as for a dog bite and the rabies serum: the quote first, the treatment second.
The CFE: the French expat's foundation, with a gap to plug
If you hold a French passport, this is where your comparison starts; if you don't, the last paragraph of this section explains why you can skip ahead. The Caisse des Français de l'Étranger bills itself as "the social security of expatriates" and offers four plans: JeunExpat (under 30), MondExpat (over 30, not yet retired), SeniorExpat (retirees) and FrancExpat, restricted to costs incurred in France during stays of under 3 consecutive months. Headline prices read on cfe.fr on 3 September 2026: from 57, 87, 147 and 46 EUR/month respectively; the actual figure comes out of the online calculator (country, age, household), since no Indonesia rate card is published in the open.
MondExpat can be taken out "with no age limit and no health questionnaire", with no possibility of exclusion, and covers hospitalisation, consultations, medicines, lab tests, maternity, dental, emergency transport and vaccines "anywhere in the world, including during your stays of under three months in France". JeunExpat carries the same cover, maternity included provided conception comes after enrolment; a salaried-worker option (daily sickness allowance, disability, death benefit) from 13 EUR/month.
Timing matters as much as price. Join before leaving or within 3 months of settling in: cover starts immediately. After that: a 3-month waiting period under 44, 6 months over 45. On returning to France, you rejoin the French social security system with no delay.
Three caveats. The CFE reimburses "on the basis of French statutory rates, often far below the actual costs" of Indonesia's private sector, as a French comparison site's guide to expat cover in Indonesia points out: hence the two classic set-ups, CFE plus an expat top-up policy, or a "first-euro" contract with no CFE at all. On price, a broker announced in February 2026 an 11% increase in contributions from 1 April 2026 (+4% for the "Ex" contracts); we could not find that announcement on cfe.fr, and nothing says whether the "from" prices above predate or postdate the rise. The official calculator settles it. Finally, the fund is for French nationals living abroad (eligibility rules on cfe.fr): a British, Australian or American expat chooses between the other three categories.
The contribution calculator is available on the Caisse des Français de l'Étranger's own site (in French), which also publishes the eligibility rules and waiting periods.
International "first-euro" insurance: the most complete, and the most expensive?
"First-euro" (au 1er euro, in the French market's jargon) means the insurer reimburses actual costs from the very first euro, with no state scheme underneath. At entry level, an international insurer's guide dated 17 June 2026 puts premiums at around 1,020 EUR/year at age 30, 1,500 EUR/year at 45 and 2,000 EUR/year at 60. On the French-speaking community side, vivreabali.fr's expat insurance guide, updated in June 2026, quotes 80 to 120 EUR/month for an essential plan, 130 to 180 EUR/month for a mid-range plan, 180 to 300 EUR/month for a comprehensive plan (worldwide, dental, optical, maternity) and 65 to 95 EUR/month under 36. The two series do not measure the same thing, but they sketch the same corridor: 80 to 300 EUR/month depending on age and tier.
This is the category that most directly meets the French foreign ministry's requirement to "cover all medical costs (including surgery and hospitalisation) and medical repatriation", because evacuation is normally part of the package. You still need to check the ceiling and the waiting periods, typically 3 months for dental, 10 to 12 months for maternity, sometimes 1 month for routine care.
Seven things to check before signing, whichever company you pick:
- direct billing with Bali's private hospitals, otherwise you front the deposit;
- evacuation and repatriation with no cap, or at least 100,000 USD;
- waiting periods, item by item;
- disclosure of pre-existing conditions and the exclusions that go with them;
- trips home (to France, in the source's example), typically 30 to 90 days a year;
- CFE compatibility, for French nationals building the fund-plus-top-up set-up;
- how the premium climbs with each age band (1,020 EUR/year at 30, 2,000 EUR/year at 60).
What is not expat insurance: standard travel insurance covers trips of under 3 months, working-holiday or long-stay travel plans 4 to 12 months; only an expat contract is an annual resident's policy. With a KITAS or another long-stay permit, travel insurance will not cover you for the long haul.
Private Indonesian insurance: the tight budget, with no safety net off the island
Local insurers sell markedly cheaper policies, priced in rupiah. Orders of magnitude from the first quarter of 2026, annual premiums: 3 to 8 million IDR at age 30, 6 to 15 million at 45, 15 to 30 million and more at 60. We leave these figures in rupiah: the sources convert them at different exchange rates.
The trade-off fits on one line: most of these policies do not cover medical evacuation, the item billed at 20,000 to more than 100,000 USD. The same seven checks apply, direct billing first of all: with no agreement in place with your insurer, the private hospital asks you for the deposit like any tourist.
BPJS Kesehatan: is the public scheme open to foreigners?
Yes, but not to all of them. The public scheme (JKN, run by BPJS Kesehatan) rests on Presidential Regulation (Perpres) No. 82/2018 of 18 September 2018, as amended by Perpres 75/2019, 64/2020 and 59/2024. Its definition of a participant includes, in translation, "any person, including a foreigner who works for at least 6 months in Indonesia, who has paid the contribution", and its Article 6 makes enrolment compulsory for every resident.
In practice, enrolment targets KITAS or KITAP holders who live and work in the country for at least 6 months, confirms the expat community site expat.or.id. The insurer's guide of 17 June 2026 adds that tourists and Second Home visa holders generally fall outside it, and that E33G (remote worker) visa holders rely on international insurance instead. The same community site states that foreign retirees are excluded; in our file, that point rests on this single source.
| BPJS category (as of 2 August 2026) | Monthly contribution | Detail |
|---|---|---|
| Self-enrolled, kelas 1 | Rp 150,000 | |
| Self-enrolled, kelas 2 | Rp 100,000 | |
| Self-enrolled, kelas 3 | Rp 42,000 | Of which Rp 7,000 subsidised: the participant pays Rp 35,000 |
| Salaried employee (PPU) | 5% of salary | 4% employer + 1% employee |
These contributions were unchanged as of 2 August 2026, according to CNBC Indonesia, cross-checked against an Indonesian comparison site (2 January 2026) and expat.or.id; IDN Times (4 January 2026) gives class 3 at Rp 25,500 after subsidy, an isolated figure we have not retained. Mind the date: the KRIS reform (Perpres 59/2024) is phasing out classes 1, 2 and 3 over roughly two years, but its rates had not been set as of 2 August 2026, the Health Minister saying at the time that no change was planned.
The limits for an expat: no English-language service, no evacuation, no cover outside Indonesia, a referral-based care pathway, and a class that is hard to change afterwards.
CFE, international, local, BPJS: the comparison in one table
| Criterion | CFE (+ top-up) | International "first-euro" | Private Indonesian | BPJS Kesehatan |
|---|---|---|---|---|
| Who it is for | French nationals abroad | Everyone | Residents | Foreigners working ≥ 6 months (KITAS/KITAP) |
| Indicative 2026 price | From 57 EUR/month (< 30), 87 EUR/month (> 30), 147 EUR/month (retirees), top-up on top | ≈ 1,020 to 2,000 EUR/year at entry level; 80 to 300 EUR/month depending on tier | 3 to 8M IDR/year at 30, 15 to 30M+ at 60 | Rp 35,000 to 150,000/month (self-enrolled), 5% of salary (employees) |
| Medical evacuation | Emergency transport listed; actual level to be confirmed, top-up often needed | Normally included, ceiling to be checked | Rarely | No |
| Outside Indonesia | Worldwide, including stays < 3 months in France | Depends on contract, 30 to 90 days/year typical | Not documented | No |
| Waiting period | None if you join before leaving or within 3 months; otherwise 3 or 6 months | Sometimes 1 month routine care, 3 months dental, 10 to 12 months maternity | Not documented | Not documented |
Before you leave: what timing avoids the waiting period?
The signing date. Join the CFE before leaving or within 3 months: immediate cover; after that, a 3- or 6-month waiting period depending on age. For a private policy, the waiting period generally runs from the start date: a contract taken out two months before arrival, with a one-month wait on routine care, has already served that period by the time you land.
The monthly budget. Broken down by month (our own calculation, not a source figure): 1,020 EUR/year is 85 EUR/month, 2,000 EUR/year is 167 EUR/month; 3 million IDR a year is 250,000 IDR/month, 8 million is 667,000. Add that line to Bali's real monthly budget before you compare rents.
The banking plan B. Even insured, keep a card whose limit can absorb a 500 to 5,000 USD deposit; a direct-billing agreement is negotiated in advance, not in the emergency room on a Sunday night. It is one line on the moving-to-Bali checklist.
Two frequent oversights: trips home (30 to 90 days a year in France for a typical expat contract; FrancExpat from 46 EUR/month for stays of under 3 consecutive months) and the permanent return (the CFE puts you straight back into the French social security system; a private policy does not play that role).
Which profile, which plan?
This article recommends no company. The typical situations, according to the sources:
- Local employee on a work KITAS: BPJS is compulsory (5% of salary, of which 4% from the employer); the question becomes the top-up, for evacuation and treatment abroad.
- E33G remote worker or digital nomad: BPJS is not the normal route; the insurer's guide of 17 June 2026 points these visas towards private international insurance.
- French national over 30, with a family: MondExpat ("from" 87 EUR/month, family rate via the calculator) with no health questionnaire, plus a top-up for actual costs; maternity is covered there, where a private policy typically imposes a 10- to 12-month waiting period.
- Under 30, tight budget: JeunExpat from 57 EUR/month for French nationals, or an essential "first-euro" plan at 65 to 95 EUR/month under 36; in both cases, check the evacuation cover.
- Retiree: SeniorExpat from 147 EUR/month for French nationals; on the BPJS side, the exclusion of foreign retirees is reported by a single source.
- Expat not eligible for the CFE: international, local or BPJS depending on your visa; evacuation first, price second.
Frequently asked questions
Is the CFE enough to get treated in Bali?
Rarely on its own. It reimburses hospitalisation, consultations, medicines, maternity, dental and emergency transport anywhere in the world, but on the basis of French statutory rates, far below Indonesian private-sector prices. Hence the two common set-ups: CFE plus an expat top-up policy, or a "first-euro" contract with no CFE. Its strengths: no health questionnaire, and immediate cover if you sign before leaving or within 3 months.
How much does health insurance cost for an expat in Bali in 2026?
CFE (French nationals): from 57 EUR/month under 30, 87 EUR/month over 30, 147 EUR/month for retirees, exact amount via the official calculator. International: around 1,020 EUR/year at 30, 1,500 EUR/year at 45, 2,000 EUR/year at 60 at entry level; on the French-speaking side, 80 to 300 EUR/month depending on the tier. Private Indonesian: 3 to 8 million IDR a year at 30. BPJS: Rp 35,000 to 150,000 a month for the self-enrolled, as of 2 August 2026.
Can a foreigner enrol in BPJS Kesehatan?
Yes, if they work at least 6 months in Indonesia (Perpres 82/2018), in practice KITAS or KITAP holders who live and work there. Tourists and Second Home visa holders generally fall outside it; E33G remote workers rely on international insurance. One community source states that foreign retirees are excluded, without corroboration in our file.
How much does BPJS Kesehatan cost per month in 2026?
For the self-enrolled, as of 2 August 2026: Rp 150,000 in class 1, Rp 100,000 in class 2, Rp 42,000 in class 3 of which Rp 7,000 is subsidised, leaving Rp 35,000 to pay. For employees, 5% of salary, of which 4% from the employer and 1% from the employee. The KRIS reform is phasing out the classes, but its rates had not been set at that date: always date the figure you use.
What happens if I am hospitalised in Bali without insurance?
You pay first. France Diplomatie warns that Indonesian hospitals provide no treatment without an insurer's guarantee of payment or, failing that, a credit card number; a Bali broker puts private hospitals' deposits at between 500 and 5,000 USD. Then: 3 to 10 million IDR a night in a private hospital, 20,000 to 50,000 USD and beyond for a serious emergency, 20,000 to more than 100,000 USD for an evacuation.
Is travel insurance enough to live in Bali?
No. Standard travel insurance covers trips of under 3 months, working-holiday or long-stay travel plans 4 to 12 months; only an expat contract is an annual resident's policy. Once settled on a KITAS or another long-stay permit, you are not durably covered by travel insurance.
How much does a medical evacuation from Bali cost?
20,000 to 40,000 USD for a commercial flight with a medical escort; an air ambulance to Singapore 50,000 to 100,000 USD according to a broker or 25,000 to 80,000 USD according to an international insurer, up to 150,000 USD and beyond from a remote island; 20,000 to 45,000 EUR on the French community side. Remember "from 20,000 to more than 100,000 USD". Neither BPJS nor most Indonesian policies cover it; the broker's recommended ceiling: at least 100,000 USD.
Sources
- (official) CFE, home page, 3 September 2026: four plans, "from" prices of 57 / 87 / 147 / 46 EUR/month.
- (official) CFE, MondExpat plan, 3 September 2026: eligibility, enrolment with no questionnaire, cover, waiting periods, return to France.
- (official) CFE, JeunExpat plan, 3 September 2026: under-30s, maternity, salaried-worker option from 13 EUR/month.
- (official) France Diplomatie, health advice for Indonesia, 3 September 2026: insurance imperative, no treatment without guarantee of payment or credit card, private hospitals, evacuation.
- (official) BPK, Perpres No. 82/2018 on Jaminan Kesehatan, 3 September 2026: record and amendments 75/2019, 64/2020, 59/2024; full text on the JDIH portal of the Indonesian Ministry of Finance.
- (media) CNBC Indonesia, 2 August 2026: kelas 1/2/3 contributions unchanged, KRIS not yet priced, Health Minister's statement.
- (media) IDN Times, 4 January 2026: classes 1 and 2 concordant; class 3 at Rp 25,500, not retained.
- (media / comparison site) Reassurez-moi, guide to expat health cover in Indonesia, 14 August 2026: CFE reimbursement at statutory rates, consultations 20-50 EUR and 40-100 EUR.
- (community) Expat.or.id, registration in the national health system: 6-month rule, classes at Rp 150,000 / 100,000 / 42,000, exclusion of retirees (uncorroborated).
- (community) Vivre à Bali, expat insurance, June 2026: tiers 80-120 / 130-180 / 180-300 EUR/month, 65-95 EUR/month under 36, waiting periods, seven checks.
- (community) Vivre à Bali, health insurance comparison, June 2026: scooter surgery 8,000-20,000 EUR, evacuation 20,000-45,000 EUR.
- (association) SPN, Mengenal Perpres 82/2018: quotations of the participant definition and Article 6.
- (commercial) "Health Insurance in Indonesia" guide by an international insurer, 17 June 2026: local and international premiums by age, visa exceptions, BPJS limits, Bali-Singapore evacuation 25,000-80,000 USD, remote island 50,000-150,000 USD and beyond.
- (commercial) Bali hospitals guide by an insurance broker, January 2026: 500-5,000 USD deposit, consultations by hospital type, emergency 20,000-50,000 USD and beyond, evacuation by mode, recommended ceiling 100,000 USD.
- (commercial) Indonesia travel insurance page of a French assistance company: consultations 200,000-500,000 IDR, specialist 500,000-1,000,000 IDR, night 3-10M IDR, travel / working-holiday / expat boundary.
- (commercial) A broker's note on 2026 CFE contributions, February 2026: +11% from 1 April 2026, not corroborated on cfe.fr.
- (commercial) BPJS guide by a Bali visa agency: cross-check of the 6-month rule.
- (commercial) BPJS Kesehatan cost page of an Indonesian comparison site, 2 January 2026: cross-check of kelas 1/2/3 contributions and 5% for employees.